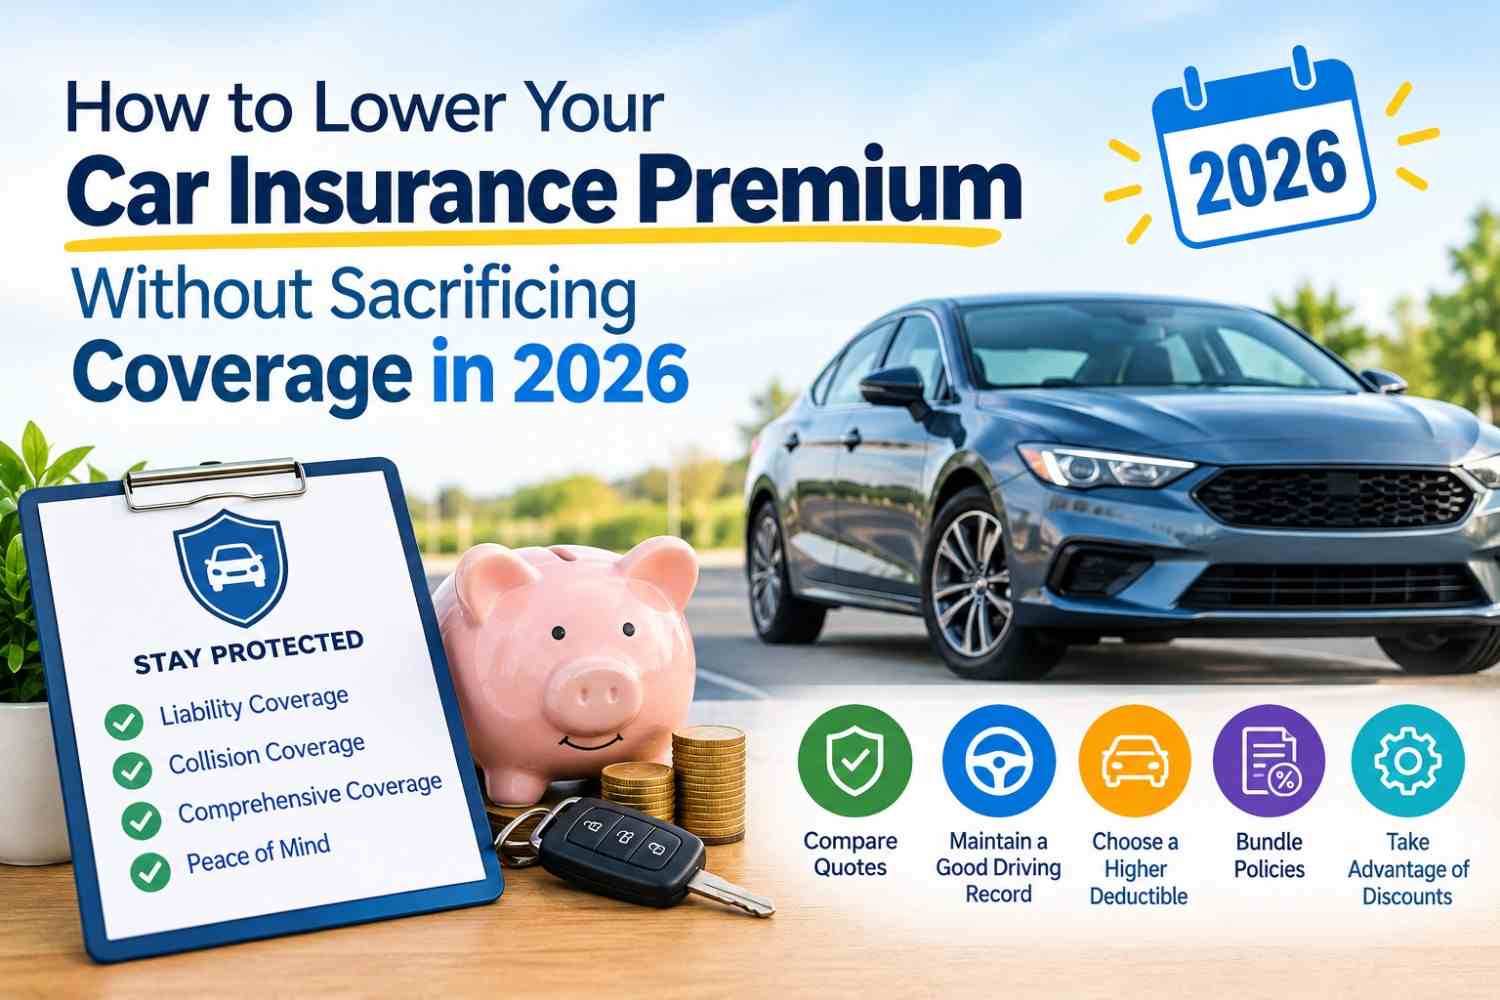
Car insurance rates have climbed steadily over the past few years, and 2026 is no exception. Between rising repair costs, more expensive vehicle technology, and inflation touching nearly every part of the claims process, many drivers are watching their lower car insurance premium creep higher every renewal cycle. The good news is that a higher bill doesn’t have to mean settling for thinner protection. With a few smart, deliberate moves, you can bring your premium down while keeping the coverage that actually matters.
1. Shop Around Every Renewal Period
Loyalty rarely pays off in the insurance world. Insurers frequently adjust their pricing models, and a company that offered you the best rate two years ago may not be competitive today. Getting quotes from at least three providers before each renewal is one of the simplest ways to make sure you’re not overpaying for the same coverage.
2. Raise Your Deductible Strategically
Increasing your deductible from $500 to $1,000 can noticeably lower your monthly premium. The key word is strategically. Only raise it to an amount you could comfortably pay out of pocket if you needed to file a claim tomorrow. This move reduces your premium without cutting the coverage limits that protect you in a serious accident.
3. Bundle Your Policies
Most insurers offer meaningful discounts when you combine auto insurance with homeowners, renters, or umbrella policies. Bundling can shave 10 to 25 percent off your total premium, and it simplifies your billing and claims process at the same time.
4. Ask About Every Available Discount
Insurers offer a long list of discounts that many drivers never claim, including safe driver discounts, low mileage discounts, good student discounts, defensive driving course discounts, and discounts for anti theft devices or telematics programs. Call your provider directly and ask which ones you qualify for. It costs nothing and can lead to real savings.
5. Improve Your Credit Score
In most states, insurers use credit based insurance scores as a factor in setting premiums. Paying down debt and keeping credit utilization low can gradually improve your score, which in turn can lower what you pay for coverage.
6. Reconsider Your Coverage, Not Cut It
Lowering a premium responsibly means reviewing your coverage rather than slashing it blindly. For example, if you drive an older vehicle with a low market value, dropping comprehensive or collision coverage might make sense. But liability limits, uninsured motorist protection, and other safety net coverages should generally stay intact, especially if you have significant assets to protect.
7. Use Usage Based or Telematics Programs
Many insurers now offer apps or devices that track your driving habits, such as braking patterns, mileage, and time of day driven. Safe, low mileage drivers can often unlock substantial discounts through these programs, sometimes without any downside if your driving habits are already solid.
8. Maintain a Clean Driving Record
This one takes time, but it’s the most reliable long term lever you have. Avoiding accidents and traffic violations keeps you out of higher risk pricing tiers, and many insurers offer accident forgiveness or safe driver rewards after a few clean years.
Frequently Asked Questions
Will raising my deductible really make a big difference?
Yes. Even a $500 increase in your deductible can lower your premium by a noticeable percentage, though the exact savings depend on your insurer and driving history.
Does bundling always save money?
In most cases yes, but it’s still worth comparing a bundled quote against separate policies from different providers to confirm you’re getting the better deal.
How often should I compare insurance quotes?
At least once a year, ideally around your renewal date, since rates and available discounts change frequently.
Can I lower my premium without lowering my coverage limits?
Absolutely. Techniques like bundling, discount stacking, telematics programs, and improving your credit score all reduce cost without touching your protection levels.

Leave A Comment