If your renewal notice made you wince this year, you are not alone. Car insurance costs have climbed for many drivers because of higher repair bills, expensive vehicle technology, and more frequent claims. The good news is that you have more control than you think. If you want to know how to lower car insurance premiums without ending up underinsured, this guide walks you through practical steps that actually work.
The goal is not to buy the cheapest policy. The goal is to pay a fair price for the protection you really need. Let’s get into it.
Why Car Insurance Premiums Keep Rising
Before you can lower your bill, it helps to understand what drives it. Insurers price your policy based on risk, and several factors feed into that calculation:
- Your age, driving history, and claims record
- Your ZIP code, including local theft, weather, and accident rates
- The make, model, and age of your vehicle
- Your credit based insurance score (in most states)
- How much you drive each year
- The coverage types and limits you choose
Some of these you cannot change quickly. Many others you can. That is where the savings are.
1. Compare Quotes From Multiple Insurers
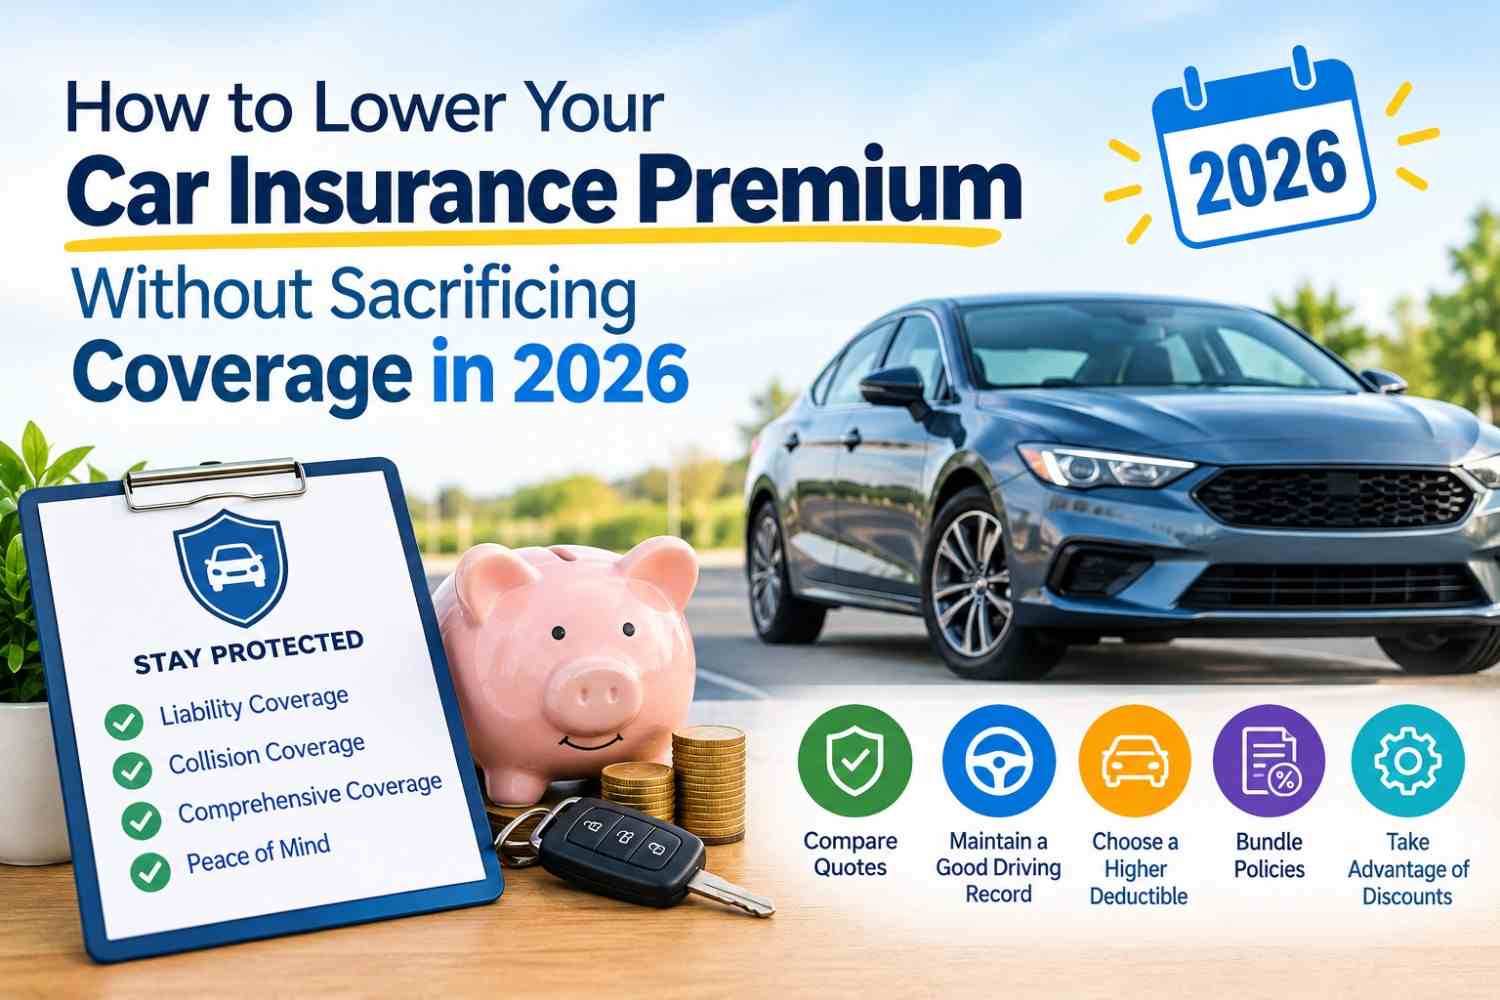
This is the single most effective way to lower car insurance premiums. Insurers weigh risk differently, so the same driver can receive very different quotes for identical coverage.
Aim to get at least three to five quotes every year, and always compare the same coverage limits and deductibles so the numbers are fair. Check national carriers, regional insurers, and independent agents who can quote several companies at once.
Loyalty rarely pays in insurance. Many companies offer their best rates to new customers, so staying with the same provider for years can quietly cost you more.
2. Bundle Your Policies
If you have home, renters, or life insurance with a different company, ask for a bundle quote. Multi policy discounts are among the most common and can reduce your premium noticeably. Always compare the bundled price against separate policies, because the cheapest combination is not always the bundle.
3. Raise Your Deductible Wisely
Your deductible is the amount you pay out of pocket before insurance covers a claim. A higher deductible usually means a lower premium, because you take on a bit more of the risk.
For example, moving from a 250 dollar deductible to a 1,000 dollar deductible on collision and comprehensive coverage can bring your premium down meaningfully. The rule here is simple: only choose a deductible you could comfortably pay tomorrow without financial stress. If an emergency fund covers it, this move can be a smart saving that does not reduce your actual protection.
4. Ask About Every Available Discount
Many drivers miss discounts simply because they never ask. Call your insurer or review your policy and ask about these:
- Good driver or accident free discounts
- Good student discounts for young drivers with strong grades
- Defensive driving course discounts
- Low mileage discounts if you drive less or work from home
- Anti theft device and safety feature discounts
- Paperless billing and autopay discounts
- Pay in full discounts if you can cover the premium upfront
- Military, alumni, and professional organization discounts
Even small discounts add up. Stacking five or six of them can make a real difference to your annual cost.
5. Consider Usage Based Insurance
Telematics programs track your driving habits through a mobile app or a small device. If you brake gently, avoid late night driving, and keep your speed reasonable, you can earn a meaningful discount.
These programs work best for careful, low mileage drivers. Read the privacy terms before enrolling, and check whether poor driving data can raise your rate, since policies differ between companies.
6. Keep Your Driving Record Clean
Your driving history carries heavy weight in pricing. Speeding tickets, at fault accidents, and DUIs can raise your premium for several years. To protect your rate:
- Follow speed limits and avoid distracted driving
- Take a defensive driving course if your state allows a discount or ticket dismissal
- Fight incorrect entries on your record when you have grounds to do so
Over time, a clean record is one of the strongest levers you have for long term savings.
7. Improve Your Credit Profile
In most states, insurers use a credit based insurance score as one pricing factor. Paying bills on time, lowering credit card balances, and avoiding unnecessary new credit applications can gradually improve your score. A better score can unlock lower rates at renewal or when you shop around.
A few states restrict or ban this practice, so check how it applies where you live.
8. Review Your Coverage, But Do Not Cut the Wrong Things
This is where many drivers make mistakes. Lowering your premium should never mean dropping protection you truly need.
Keep strong liability limits. State minimum coverage is often too low to cover a serious accident. If you cause major damage or injury, you could be personally responsible for costs beyond your limits. Higher liability coverage is usually inexpensive relative to the protection it gives.
Keep uninsured and underinsured motorist coverage. Many drivers on the road are uninsured or carry minimal coverage. This protection covers you when the other driver cannot.
Review collision and comprehensive on older cars. If your vehicle is worth only a few thousand dollars, paying for full coverage may no longer make financial sense. A simple test is to compare your annual cost for these coverages against your car’s market value. If the premium is a large share of what the car is worth, adjusting may be reasonable.
The smart approach is to trim what is redundant, not what is essential.
9. Choose Your Vehicle Carefully
If you are shopping for a new or used car, insurance should be part of the decision. Vehicles that are costly to repair, frequently stolen, or built for high performance tend to cost more to insure. Cars with strong safety ratings and modern driver assistance features often earn better rates.
Before you buy, request an insurance quote for the exact model you are considering. It can save you from an unpleasant surprise.
10. Reduce Your Annual Mileage
The less you drive, the lower your risk, and insurers reward that. If your commute has changed, or you now work remotely, update your estimated annual mileage. Many people overestimate their driving and overpay as a result. Be honest and accurate, because misreporting mileage can cause problems if you file a claim.
11. Remove Unnecessary Drivers and Update Your Details
Make sure your policy lists only active drivers and vehicles. If a family member has moved out, or you sold a car, update your policy so you are not paying for coverage you no longer use. Also confirm that your address, vehicle details, and marital status are current, since these can all influence pricing.
12. Review Your Policy Every Year
Your life changes, and so do insurance prices. Set a yearly reminder to review your policy at least thirty days before renewal. A quick review gives you time to compare quotes, ask for new discounts, and adjust coverage based on your current needs.
Major life events are also good moments to recheck your policy, such as moving, buying a new car, getting married, or changing jobs.
Common Mistakes to Avoid
- Choosing the cheapest policy without comparing coverage
- Letting your policy lapse, which can raise future rates
- Setting a deductible you cannot afford to pay
- Assuming your insurer will automatically give you the best price
- Ignoring customer service and claims reputation while chasing a low price
A low premium means little if the company is difficult to deal with when you actually need help.
Quick Action Checklist
- Gather your current policy details and coverage limits
- Request quotes from at least three to five insurers
- Ask each company about every discount you may qualify for
- Compare deductibles and consider a higher one if you have savings
- Bundle policies if the total price is lower
- Keep strong liability and uninsured motorist protection
- Review and renew your comparison every year
Final Thoughts
Learning how to lower car insurance premiums is really about being informed and a little proactive. Shop around, claim every discount, adjust your deductible with care, and protect your driving record and credit. Most importantly, keep the coverage that protects your finances in a serious accident.
With a few smart moves, you can pay less in 2026 and still drive with confidence.
Frequently Asked Questions
What is the fastest way to lower car insurance premiums?
Comparing quotes from several insurers is usually the fastest and most effective method. Pair it with a discount review for even better results.
Will raising my deductible really lower my premium?
Yes, in most cases. A higher deductible shifts more of the initial cost to you, so insurers charge less. Just make sure you can afford the deductible if you need to file a claim.
Is it safe to switch insurance companies often?
Switching is fine as long as you avoid any gap in coverage. Start the new policy before cancelling the old one.
Does full coverage make sense for an older car?
It depends on the car’s value and your finances. If the cost of collision and comprehensive is high compared to the car’s worth, you may consider reducing it, but keep liability coverage strong.
How often should I review my car insurance?
At least once a year, and also after major life changes like moving, buying a car, or adding a driver.

Leave A Comment